All Categories
Featured
The Tax Advantages of Permanent Life Policies for Retirees
Why EPO Plans are the Smart Choice for Modern Families

Securing Coverage for Seniors
Table of Contents
Premiums are normally lower for HMO plans, and there is usually no deductible or a low one. Some HMO strategies, including those used by Medical Mutual, do not need you to choose a PCP or have a referral to see a professional. For more HMO specifics, read our About HMO Plans short article.
They also include a network of suppliers, but there are less limitations on seeing non-network service providers. In addition, your PPO insurance will pay if you see a non-network provider, although it may be at a lower rate. Here are some crucial functions: You can see the doctor or expert you 'd like without having to see a PCP.
Your benefits will be much better if you stay in the PPO network. Premiums tend to be higher, and it prevails for there to be a deductible. Read a more detailed definition of PPO in our PPO Plans post. As mentioned above, Distinctions in between HMO (Health Care Company) and PPO (Preferred Service provider Company) plans consist of network size, ability to see experts, costs, and out-of-network protection.
Essential Part D Selection Tips for 2026
A specifying feature of HMO and PPO plans is that they both have networks. Networks are one method to lower health care expenses network service providers concur to offer discount rates in exchange for access to a health strategy's members.
In general, PPO networks tend to be broader, including more medical professionals and health centers than HMO strategies, giving you more choice. Nevertheless, networks will differ from insurance provider to insurance provider, and strategy to strategy, so it's best to research each strategy's network before you decide. Many HMOs will need you to select a medical care physician, who will be the main point of contact for your medical care.
Costs for specialists will not be covered without a PCP recommendation. On the other hand, PPOs tend not to need choice of a PCP, and you can generally see a specialist without a referral, and still have actually these costs covered. For both PPO and HMO strategies, your costs for care will be least expensive if you receive it from in-network providers.
For HMOs, out-of-network services are generally not covered at all, except for emergency situations. PPOs vary from HMOs because PPO strategies will generally provide some coverage for these types of services, however coverage for in-network providers will be much better. The additional protection and flexibility you get from a PPO means that PPO plans will normally cost more than HMO plans.
Asset Security Using Modern Life Insurance
Another cost to consider is a deductible. This is the amount of health care expenses you must pay before your plan begins to cover your costs. Not all HMOs have deductibles, however when they do, they tend to be lower than PPO deductibles. You can find out more about health insurance expenses in our Comprehending Medical Insurance Costs article.
49% of covered employees had PPO plans in the study, while HMOs covered 16%. When it pertains to your own health plan choice, it might sound like a cliche, but when picking between an HMO or PPO strategy, it is not always about which is much better, but which is finest for you.
If your monetary circumstance dictates that expense is crucial, you may seriously think about going with an HMO strategy. Usually speaking, costs for HMO plans will be less. Premiums tend to be lower, and deductibles will also be lower, or may be missing totally. The compromise will be versatility, nevertheless.
Independent Insurance AgencyUnlike many HMO health insurance, you won't likely require to pick a main care physician, and you won't usually require a referral from that physician to see an expert. A PPO network will likely be bigger, offering you a greater selection of in-network medical professionals, professionals, and centers to select from.
Evaluating PPO and HMO Insurance
With HMOs, out-of-network protection will normally be limited to emergencies; non-emergency services are not usually covered at all. To assist you weigh the advantages and disadvantages described above, here's a quick summary of them: With any plan, examine the provider network to see if your preferred service providers remain in the strategy's network, because staying in-network will conserve you cash.
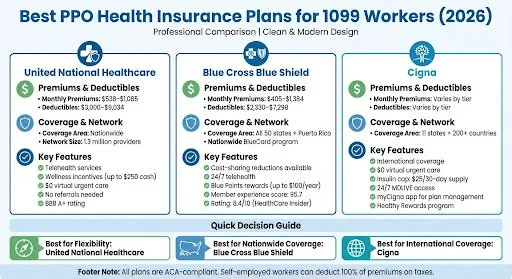
You may discover that the particular HMO plan you're considering contains your favored suppliers, or a minimum of enough of them to fulfill your needs. If you're considering a Medical Shared plan, you can check our networks before you use. For tips on selecting the very best medical insurance prepare for your requirements, see our article on Comparing Health Insurance Plans.

Latest Posts

Benefit Strategies for US Veterans

The Tax Advantages of Permanent Life Policies for Retirees
Why EPO Plans are the Smart Choice for Modern Families