All Categories
Featured

Finding Best Medicare Supplement Coverage for 2026
Table of Contents
HHS prepares to broaden access to disastrous health protection through its new challenge exemption assistance, the department revealed today.
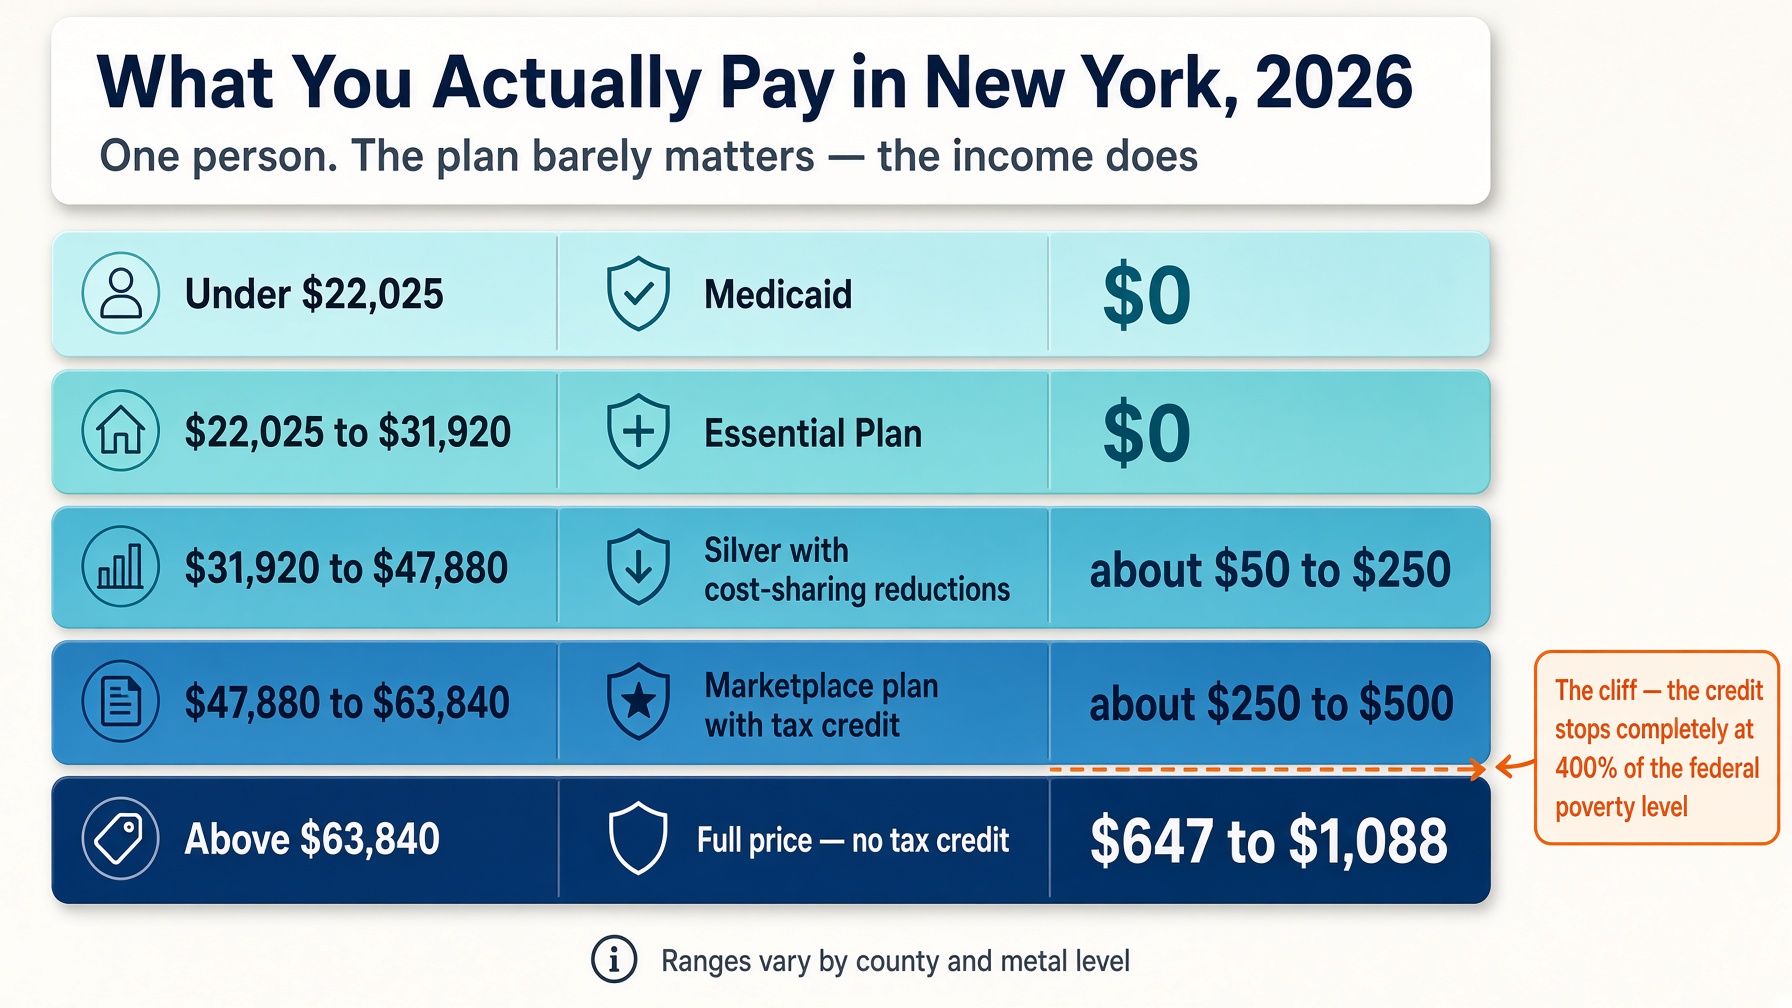
HHS' new challenge exemption assistance will make it simpler for people to gain access to disastrous coverage if they are disqualified for advance payments of the premium tax credit (APTC) or cost-sharing decreases (CSRs), based on their yearly household income. Usually, customers who are newly disqualified for APTC or CSRs due to their projected yearly earnings being listed below 100% or above 400% of the federal poverty line are eligible for a difficulty exemption and can enlist in catastrophic coverage.
The modifications were driven by predicted boosts in health insurance premiums for the 2026 strategy year across the individual market, CMS stated in an accompanying fact sheet. Rate increases could lead to difficulties with getting coverage under a Qualified Health Plan, particularly for those whose earnings makes them disqualified to get APTC or CSRs.
Insurance in Chino Hills CAFinding 2026 Medicare Advantage Coverage
"Catastrophic coverage offers inexpensive health insurance for younger Americans and those dealing with challenge to have security when they require it most," HHS Secretary Robert F. Kennedy, Jr. said in the announcement. "Expanding access to disastrous coverage is another action in making health insurance more economical, building on the progress made because the passage of President Trump's One Big Beautiful Expense.".
NAIFA has actually long promoted for access to inexpensive catastrophic health plan alternatives. Under the brand-new policy, customers who are not qualified for advance payments of superior tax credits or cost-sharing decreases on the Health Insurance Marketplace are eligible for difficulty exemptions allowing them to acquire catastrophic strategies starting November 1.
They likewise cover preventative services needed under the Affordable Care Act and as much as three pre-deductible sees with medical care physicians. The exemption will use to consumers purchasing plans either on or off the Exchange. Beginning November 1, 2025, customers can request the hardship exemption in two methods: Use online for Marketplace protection on or through a licensed partner.
Submit a difficulty exemption form by mail. HHS is also simplifying the procedure by enhancing the review of paper applications to reduce the administrative concern on customers. This change will make it easier for people experiencing challenge and seeking a devastating strategy to access the complete variety of catastrophic protection options readily available to them.
Reviewing New Life Insurance Benefits for Veterans
Pennsylvania household medical insurance for 2026 runs on two parallel tracks that typically apply simultaneously to households with children. The Pennie marketplace covers adults and family systems with federal premium tax credits and Silver cost-sharing reductions. Pennsylvania CHIP covers kids under 19 in families earning as much as 319 percent of the federal poverty line approximately $102,521 for a family of 4 through a different, usually more extensive and less costly program.
Insurance in Chino Hills CAUnderstanding both tracks is the crucial to finding the least expensive overall family protection expense in 2026. Mixed-race household of four at a Bethlehem kitchen table evaluating 2026 Pennsylvania family medical insurance and CHIP alternatives Pennsylvania CHIP covers kids under 19 in households earning up to 319 percent of the federal poverty line roughly $102,521 for a household of 4 in 2026.
CHIP Tier Income Range (Family of 4) Month-to-month Premium Copays Medical Help (children)Under $54,395 (under 215% FPL)$0None Free CHIP$ 54,395$66,120 (215%258% FPL)$0Minimal ($5$10) Low-priced CHIP$ 66,120$89,750 (258%350% FPL)$30$75/child/mo$10$20 per see Full-Cost CHIP$ 89,750$102,521 (350%319%?
Consumer Advice for Buying 2026 Medicare Insurance
Pennsylvania CHIP is administered through 7 handled care providers, each covering specific counties. Carrier availability determines which CHIP plan a household picks not all CHIP providers run statewide. At enrollment, the Pennie or COMPASS system provides the CHIP providers readily available at the household's address. Families then select their preferred CHIP carrier for each qualified child, and the carrier manages all plan benefits, authorizations, and client service for that child.
A Self-reliance Blue Cross Pennie prepare for moms and dads coupled with Self-reliance Blue Cross CHIP for children creates a consistent provider network and lowers coordination intricacy. When possible at the same premium level, matching CHIP and Pennie providers within a household streamlines provider selection for children's experts who accept both programs.

Latest Posts
Evaluating PPO and HMO Medical Coverage
Reviewing Whole Life versus Term Benefits
Choosing Medicare Advantage Coverage