All Categories
Featured


Direct Consumer Advice for Choosing Coverage
One of the most attractive functions is the capability to access the money worth through policy loans and withdrawals, frequently on a tax-free basis, provided the policy is structured correctly and remains in force. Policy loans are usually ruled out gross income. Withdrawals approximately the amount of premiums paid (your cost basis) are generally tax-free.
It's important to understand that if the policy lapses or is given up, impressive loans and gains may become taxable. The adjustable premium payments and potential death benefit choices offer a degree of flexibility not constantly found in other long-term life insurance coverage products. While concentrating on cash development, the policy still supplies an important survivor benefit for recipients, offering monetary defense for your liked ones.
The "finest IUL policies for cash accumulation" will usually feature competitive caps, participation rates, and manageable internal costs. The "best business for IUL" for retirement planning might likewise provide favorable loan arrangements. But remember, these functions should be examined together. A high cap may be offset by high charges or a low participation rate.
Since today's cap is not the whole story, our comparison of IUL renewal cap rates: F&G vs Pacific Life and Lincoln takes a look at how caps have changed in time. While IUL offers engaging potential advantages, it's important to approach it with a clear understanding of the associated dangers and expenses.
Final Expense Coverage Guide
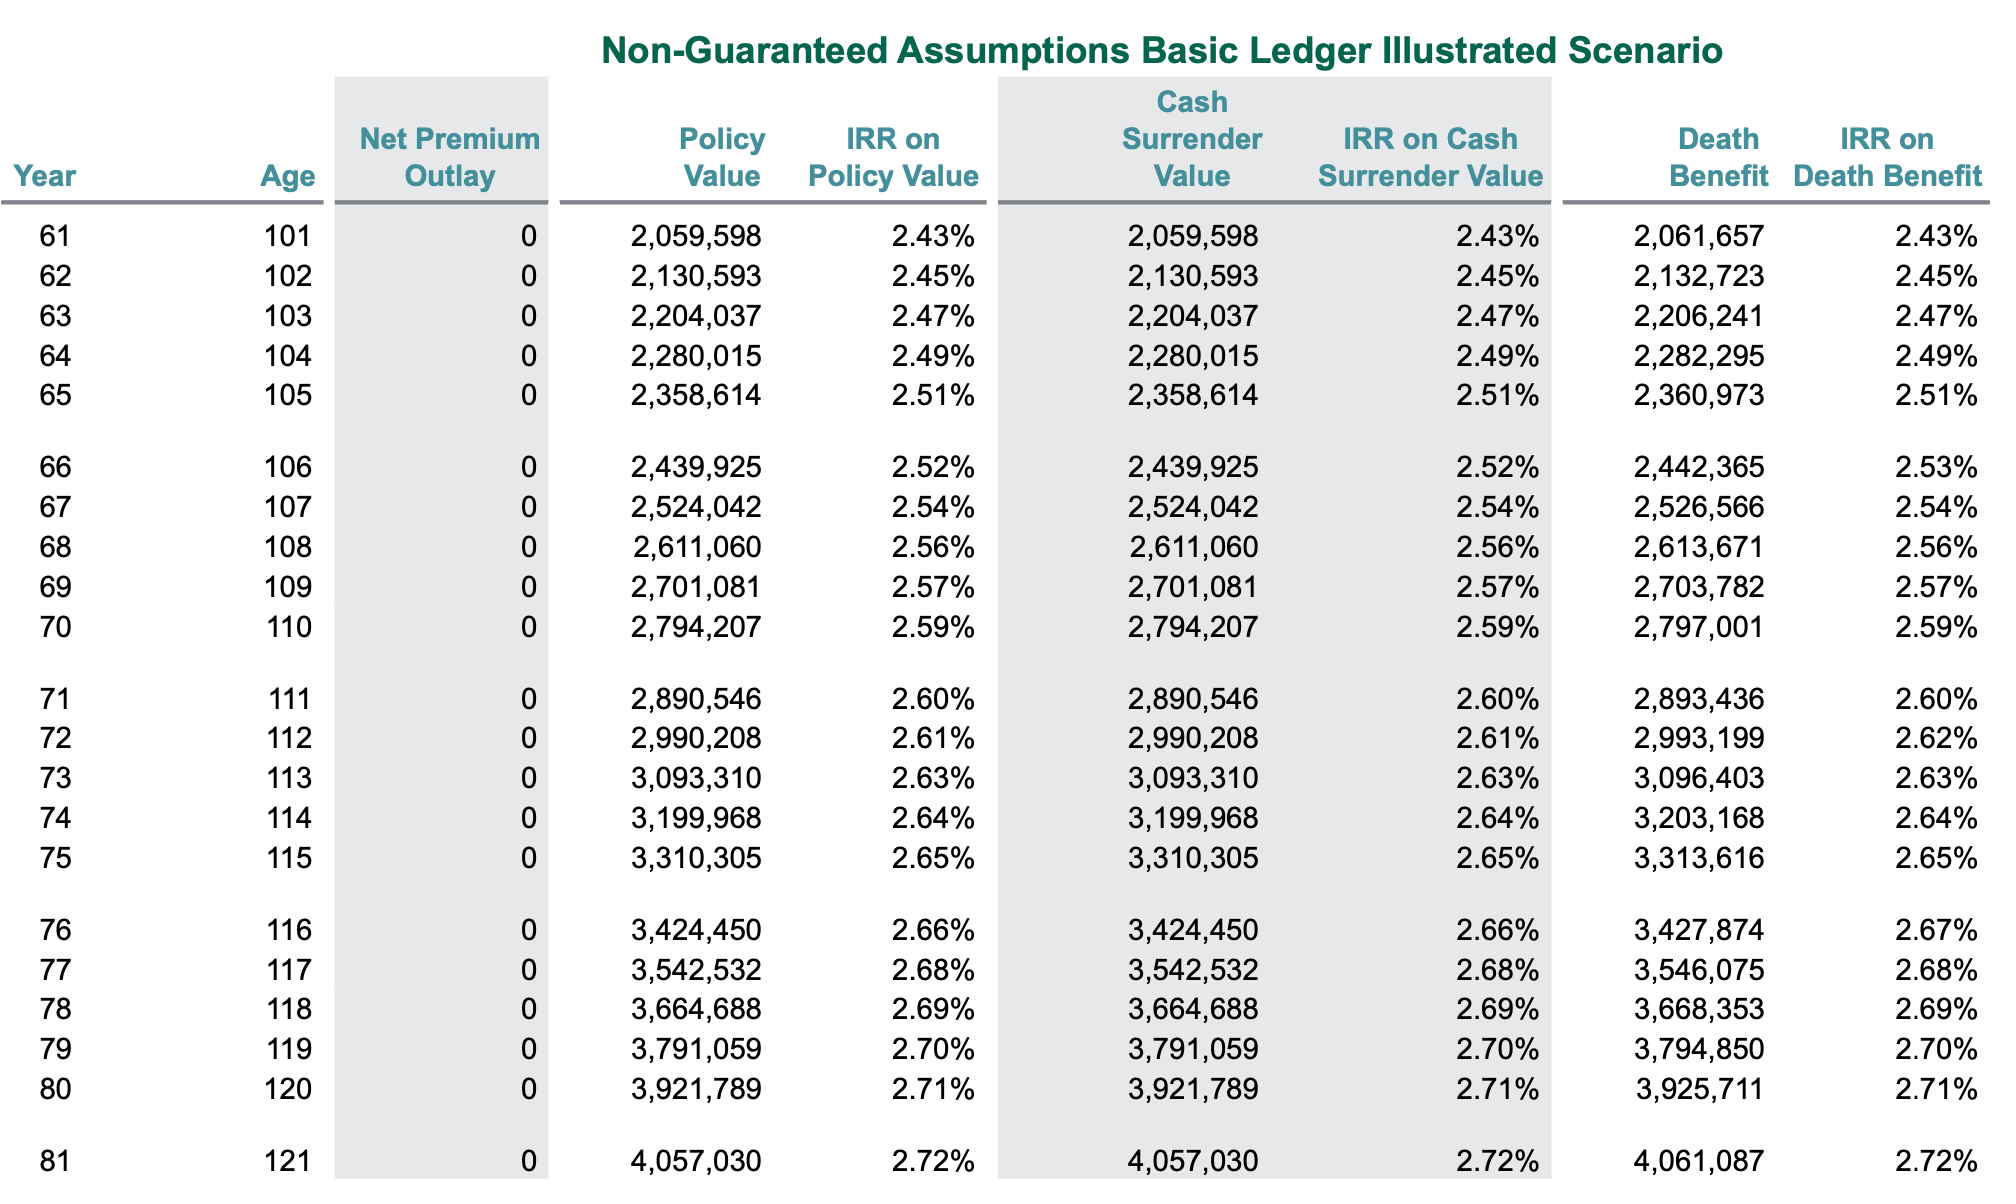
IUL policies are naturally more intricate than term life or even conventional whole life. Policy illustrations, which forecast future cash worth development, are based on various assumptions about index efficiency, crediting rates, policy costs, and loan usage.
Medicare in OntarioIt's essential to evaluate illustrations based upon conservative presumptions and ensured elements, not just the most favorable circumstances. IUL policies have different internal charges that minimize cash worth growth. These can include: The charge for the pure death benefit security. This generally increases with age. A percentage deducted from each premium payment.
Costs for any additional advantages added to the policy. Costs applied if you give up the policy or withdraw significant quantities, normally within the very first 10-15 years.
While the floor protects against direct market * losses *, it does not ensure favorable returns. If the connected index carries out improperly or stays flat for extended durations, your cash worth might only make the floor rate (often 0%). After policy expenses are deducted, the money worth could possibly decrease in such years.
Even in booming market years, your credited interest won't exceed the cap. Involvement rates listed below 100% further minimize the credited interest relative to the index gain. Providers can often adjust non-guaranteed components like caps and participation rates over the life of the policy (within legal limitations), which could affect long-lasting performance.

Latest Posts
Evaluating PPO and HMO Medical Coverage
Reviewing Whole Life versus Term Benefits
Choosing Medicare Advantage Coverage