All Categories
Featured


Comparing Family Health Rates
Table of Contents
Readily Available Development OptionsUnderlying Cost StructureParticipating Loan RatesCompany Credibility (because much of the above will not be ensured)Since IUL cap rates, participation rates, and loan rates have been a moving target varying hugely, we did not desire to post real numbers just to have them become obsolete a month or 2 later on.
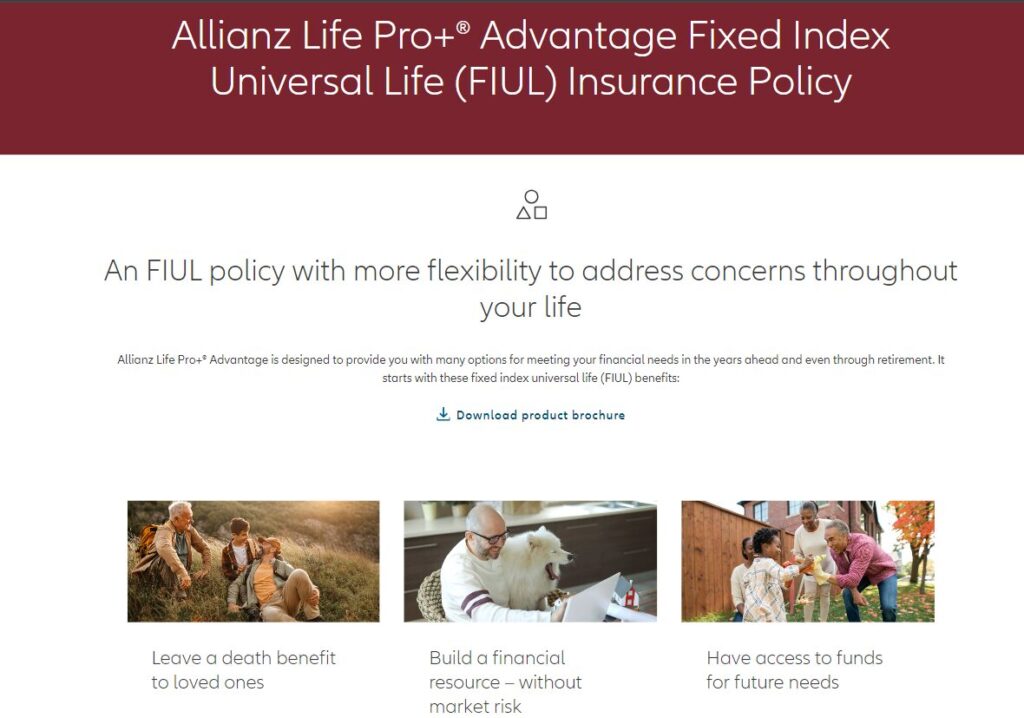
Indexed Universal Life policies include costs, caps, involvement rates, spreads, policy charges, and loan risk. Policy loans and withdrawals might decrease money worth and death benefit, may cause the policy to lapse, and might develop taxable income if not handled properly.
Updated September 13, 2026Searching for the "best IUL companies" or the "best IUL policies for money accumulation" in 2025? You're not alone. Indexed Universal Life (IUL) insurance coverage has gotten considerable attention as a financial tool that integrates a survivor benefit with the potential for money value growth linked to market indexes, often pitched as a part of a retirement strategy.
Final Expense Insurance Benefits
The ideal policy and business depend totally on your unique financial objectives, threat tolerance, health, and timeline. Understanding IUL requires navigating a landscape of caps, floorings, participation rates, charges, and complicated illustrations.
That's where goal, independent guidance becomes important. Welcome to Insurance Coverage By Heroes. We're an independent insurance coverage firm established by a previous first responder and military spouse, and staffed by specialists with backgrounds rooted in civil service. Our mission isn't just to sell insurance coverage; it's to serve and educate our clients, assisting them browse intricate financial items like IUL.
This independence allows us to objectively shop the market, compare the best IUL items available, and tailor coverage particularly to your specific needs and goals. We believe in finding the ideal fit for you, not pushing a one-size-fits-all solution.
Low-Cost Individual Medical Insurance
At its core, Indexed Universal Life is a kind of long-term life insurance coverage policy. Unlike term insurance coverage, which covers you for a specific duration, long-term policies like IUL are created to last your entire lifetime, supplied premiums are paid and the policy remains in force. IUL policies have a number of essential parts: This is the primary function of any life insurance coverage policy.
IUL uses flexibility in death benefit amounts, which can in some cases be changed over time. This is the specifying feature of IUL.
You are not straight investing in the index itself. Insurance business utilize different techniques to determine the interest based on index performance.
Comparing Medicare Advantage Options
Some policies use 100% and even greater participation rates, but this typically features other trade-offs. A lot of IUL policies have a cap, which is the optimum interest rate that can be credited to your money value in a provided period, despite how high the selected index performs. If the index gains 15%, the participation rate is 100%, but the cap is 9%, your cash value would be credited with 9% interest (before fees).
Insurance in Palm Desert CAFinding the very best IUL carrier frequently includes comparing existing and historical cap rates, but this is just one piece of the puzzle. This is an important protective function of IUL. The floor is the minimum rates of interest your policy can make, even if the connected index experiences losses. A lot of typically, the floor is 0%.
Like other universal life policies, IUL provides flexibility in premium payments. It's instantly clear that the interaction in between these elements produces substantial variation amongst the IUL policies offered by different companies.
An independent firm like Insurance By Heroes is necessary for comparing these complex information across several leading IUL companies. The search keywords "best IUL for money accumulation" and "finest IUL for retirement" emphasize this typical interest.

Latest Posts
Evaluating PPO and HMO Medical Coverage
Reviewing Whole Life versus Term Benefits
Choosing Medicare Advantage Coverage